SlideServe
Menu
Préférences
© SlideServe · v2026

Scenario #1

jaron avatar
11 diapositives · 352 Views · Oct 23, 2014

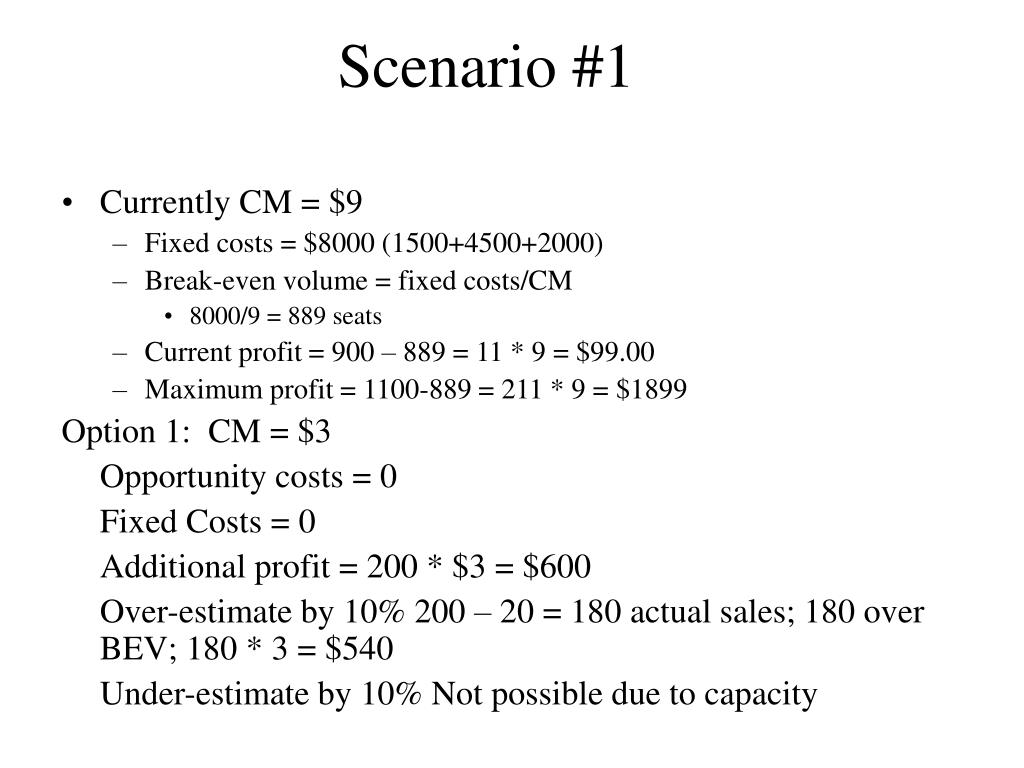
Scenario #1. Currently CM = $9 Fixed costs = $8000 (1500+4500+2000) Break-even volume = fixed costs/CM 8000/9 = 889 seats Current profit = 900 – 889 = 11 * 9 = $99.00 Maximum profit = 1100-889 = 211 * 9 = $1899 Option 1: CM = $3 Opportunity costs = 0 Fixed Costs = 0
Scenario #1 - slide 1
01 / 11Scenario #1
1 / 17

Télécharger la présentation

Scenario #1
Une image / un lien ci-dessous est fourni (tel quel) pour télécharger la présentation

Politique de téléchargement : le contenu du site vous est fourni TEL QUEL pour votre information et votre usage personnel ; il ne peut être vendu, concédé sous licence ni partagé sur d’autres sites sans l’accord de son auteur.Le contenu vous est fourni TEL QUEL, pour votre information et votre usage personnel uniquement. Téléchargez la présentation en cliquant sur ce lien. Lors du téléchargement, si vous ne parvenez pas à télécharger une présentation, l’éditeur a peut-être supprimé le fichier de son serveur.Pendant le téléchargement, si vous ne parvenez pas à obtenir une présentation, le fichier a peut-être été supprimé par l’éditeur.

F I N

Plus de contenu associé

Transcription de la présentation
  1. Scenario #1 • Currently CM = $9 • Fixed costs = $8000 (1500+4500+2000) • Break-even volume = fixed costs/CM • 8000/9 = 889 seats • Current profit = 900 – 889 = 11 * 9 = $99.00 • Maximum profit = 1100-889 = 211 * 9 = $1899 Option 1: CM = $3 Opportunity costs = 0 Fixed Costs = 0 Additional profit = 200 * $3 = $600 Over-estimate by 10% 200 – 20 = 180 actual sales; 180 over BEV; 180 * 3 = $540 Under-estimate by 10% Not possible due to capacity

  2. Scenario #1 • Option 2: • CM = $5 • Opportunity costs = $150 * 9 = $1350 • Incremental costs = $2000 • Total costs = $3350 • Break-even volume = $3350/5 = 670 seats • Additional profit = 700-670 = 30*5 = $150 • Potential profit = 1100-670 = 430*$5 = $2150 • Over-estimate by 10% = 700-70 = 630 actual; 630-670 = -40 under BEV; -40 * 5 = (200) • Under-estimate by 10% = 700 + 70 = 770 actual; 770 – 670 = 100 over BEV; 100 * 5 = $500

  3. Scenario #1 • Option 3: • CM = $9 • Opportunity costs = 100 * 9 = $900 • Incremental costs = $6500 • Total Costs = $7400 • Break-even volume = 7400/9 = 822 seats • Additional profit = 800-822 = -22 * 9 = ($198) • Potential profit = 1100 – 822 = 278 * 9 = $2502 • Over-estimate by 10% 800 – 80 = 720 actual; 720 – 822 = -102; -102 * 9 = ($918) • Under-estimate by 10% 800 + 80 = 880 actual; 880 – 822 = 58 over BEV; 58 * 9 = $522

  4. Scenario #2 • Current CM = $9.50 • Fixed costs = 1500+4500+1200 = $7200 • BE volume = fixed costs/CM • 7200/9.50 = 758 seats • Current profit = 900-758 = 142 * $9.50 = $1349 • Maximum profit = 1100-758 =342*$9.50 = $3249

  5. Scenario #2 • Option #1 CM = $3.50 • Additional profit = 200 seats * $3.50 = $700 • Overestimate by 10% = 200-20=180 seats • 180 over BEV * $3.50 = $630 • Underestimate by 10% is not possible due to space limitations

  6. Scenario #2 • Option #2 CM = $5.50 • Opportunity costs = 150 * $5.50 = $825 • Incremental costs = $1200 (perf. Costs) • Total costs = $1200 + $825 = $2025 • BE volume = 2025/$5.50 = 368 tickets • Additional profit = 700-368=332 seats * 5.50 = $1826 • Potential profit = 1100-368 = 732 seats * $5.50 = $4026 • Overestimate by 10% = 700-70 = 630 actual • 630 – 368 seats = 262 over BEV * $5.50 = $1441 • Underestimate by 10% = 700+70 = 770 actual • 770-368 = 402 seats * $5.50 = $2211

  7. Scenario #2 • Option #3 CM = $9.50 • Opportunity costs = 100 * $9.50 = $950 • Incremental costs = $5700 (perf + rehearsal) • Total costs = $6650 • BE Volume = 6650/9.50 = 700 seats • Additional profit = 800 – 700 = 100 * 9.50 = $950 • Potential profit = 1100-700 = 400 * 9.50 = $3800 • Overestimate by 10% = 800-80 = 720-700=20*9.50 = $190 • Underestimate by 10% = 800+80 = 880-700=180*9.50 = $1710

  8. Scenario #3 • Current CM = $7.00 • Fixed costs = $6000 • BE volume = 6000/7 = 857 seats • Current profit = 900-857 = 43 seats * 7 =$301 • Maximum profit = 1100-857 = 243 seats * 7 = $1710

  9. Scenario #3 • Option #1 CM = $1 • Additional profit = 200 * $1 = $200 • Overestimate by 10% = 200-20 = 180 * 1=$180 • Underestimate by 10% - not possible

  10. Scenario #3 • Option #2 CM = $3 • Opportunity costs = $150 *3=$450 • Incremental costs = $2000 (perf. Costs) • Total costs = $2450 • BE Volume = 2450/3=817 seats • Additional profit = 700-817=(117)*3=($351) loss • Potential profit = 1100-817 = 283*3=$849 • Overestimate by 10% = 700-70=630-817=(187)*3 = ($516) loss • Underestimate by 10% = 700+70=770-817=(47)*3=($141) loss

  11. Scenario #3 • Option #3 CM = $6 • Opportunity costs = $100*6=$600 • Incremental costs = $4500 (perf + rehearsal) • Total costs = $5100 • BE Volume = $5100/$6=850 seats • Additional profit = 800-850 = (50)*6=($300) loss • Potential profit = 1100-850 = 250*6=$1500 • Overestimate by 10% = 800-80=720-850=(130)*6=($780) loss • Underestimate by 10% = 800+80=880-850=30*6=$180