
Understanding Portfolio Diversification and the Efficient Frontier in Finance

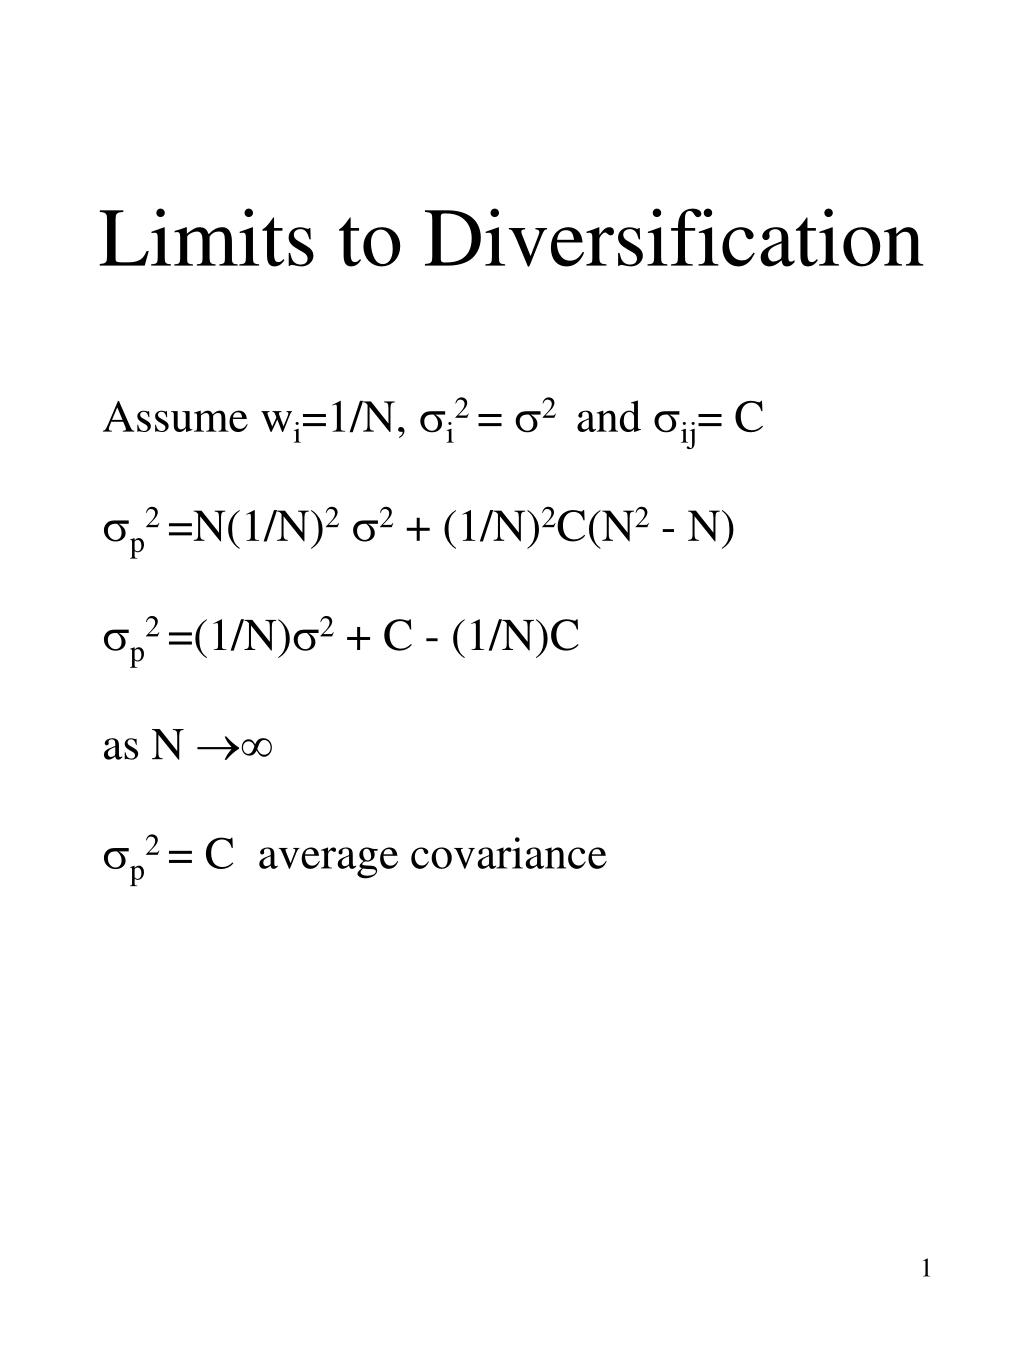
This text explores key concepts in portfolio theory, including the limits of diversification, the role of risk-free securities, and the efficient frontier. It outlines the mathematical foundations of portfolio risk and return, emphasizing the separation theorem and the capital market line. It highlights assumptions such as investors' mean-variance preferences, the distribution of asset returns, and the absence of market frictions. Key relations like the Capital Asset Pricing Model (CAPM) and the contribution of individual stocks to portfolio risk are also examined, providing essential insights for investors.
Télécharger la présentation 
Politique de téléchargement : le contenu du site vous est fourni TEL QUEL pour votre information et votre usage personnel ; il ne peut être vendu, concédé sous licence ni partagé sur d’autres sites sans l’accord de son auteur.Le contenu vous est fourni TEL QUEL, pour votre information et votre usage personnel uniquement. Téléchargez la présentation en cliquant sur ce lien. Lors du téléchargement, si vous ne parvenez pas à télécharger une présentation, l’éditeur a peut-être supprimé le fichier de son serveur.Pendant le téléchargement, si vous ne parvenez pas à obtenir une présentation, le fichier a peut-être été supprimé par l’éditeur.
F I N